"The website uses Cookies and other relevant technologies to optimize services. To provide you with a better experience, if you continue to use our site, you are consenting with our use of Cookies.
The website can also find scenic spots for users. To activate and utilize this AI-based service, please allow the site to acquire your location first."
TIPC conducts a materiality analysis in accordance with the eight reporting principles outlined in the GRI Standards 2021: Accuracy, Balance, Clarity, Comparability, Completeness, Sustainability Context, Timeliness, and Verifiability. The sustainability issue management process follows the four-stage approach outlined below:
STEP1
Identification of Stakeholders
Stakeholders Inclusiveness
11
Categories of Stakeholders
Through consultations and feedback from external experts, department heads, and employees, as well as cross-functional discussions, TIPC identified a comprehensive range of stakeholder groups by considering stakeholders identified in previous assessments and those recognized by industry peers. These stakeholder groups serve as the primary audiences for engagement and communication on material topics.
In 2025, TIPC identified and categorized 11 key stakeholder groups: government authorities, shareholders/investors, employees, customers, elected representatives, equity investment businesses, suppliers/contractors, local governments, media, community residents/local organizations, and industry, professional, and academic associations.
STEP2
Prioritization of ESG Topics
Sustainability Context
26
Topics of Concern
Taking the sustainability context into consideration, TIPC developed a pool of topics for materiality assessment by referencing the GRI Standards, SASB Standards, Sustainable Development Goals (SDGs), and material topics identified by industry peers. A total of 26 topics spanning three dimensions—economic (including governance), environmental, and social (including human rights)—were identified and used as the basis for assessing, scoring, and prioritizing both positive and negative impacts.
STEP3
Identification of Material Topics
Materiality
32
Questionnaires Received
(Survey of First-Level Supervisors)
100% agreed to retain the
17
material topics identified in 2024 Meeting resolution:
16
Material Sustainability Topics
In 2024, a total of 54 questionnaires were collected from internal executive-level management, and the results were cross-analyzed with evaluations by external experts. Topics across the economic, environmental, and social dimensions that could significantly impact the Company’s sustainable development were evaluated and scored. Topics with an average score of 3.5 or above were identified as material topics. As a result, the Company identified 17 material ESG topics for 2024.
In 2025, TIPC conducted a material topic survey among chiefs of staff and above at each branch company, as well as first-level managers and above at Headquarters, receiving a total of 32 responses. All respondents agreed to retain the existing material topics identified in the previous assessment. The 2024 materiality assessment results were subsequently reviewed by internal management and external experts during the Material Topics Identification Meeting. Considering that TIPC is a state-owned enterprise whose operations are conducted in accordance with applicable laws and regulations, and that GRI 2-27 (Compliance with Laws and Regulations) is a mandatory disclosure requirement, the meeting resolved not to identify Regulatory Compliance as a separate material topic in 2025. Relevant compliance information will instead be disclosed in the Sustainability Report in accordance with GRI 2-27 requirements.
The 16 material topics identified for 2025 are: 1. Climate Change Risks and Opportunities, 2. Information Security and Customer Privacy, 3. Green Investment, 4. Supplier Management, 5. Operational Risk Management, 6. Customer Service Quality, 7. Economic Performance, 8. Integrity Governance, 9. Business Model Optimization and Innovation, 10. Safety Management of Port Operations, 11. Occupational Safety and Health, 12. Employee Development and Engagement, 13. Greenhouse Gas Emissions, 14. Air Pollution, 15. Energy Management, 16. Employee Benefits.
STEP4
Review and Discussion
Principle of Completeness
Following the identification of material topics and their respective boundaries, TIPC incorporates priority topics into its annual plans and objectives. The Company will continue to strengthen its management mechanisms, regularly review material topics and make necessary adjustments, and disclose relevant information in the Sustainability Report.
Material Topics Prioritization
By applying the GRI Standards 2021 and incorporating relevant GRI Sector Standards into the assessment process, TIPC followed the materiality identification process described above. Based on the results of the previous year’s assessment, the Company retained and confirmed 16 material topics for the current reporting year.
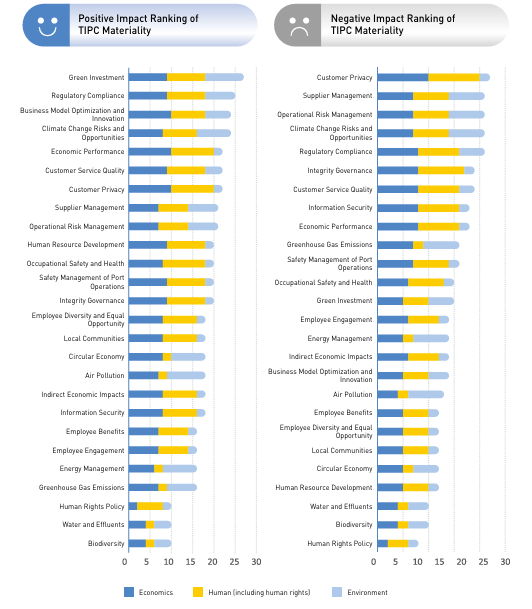
Positive Impact Ranking & Negative Impact Ranking of TIPC Materiality
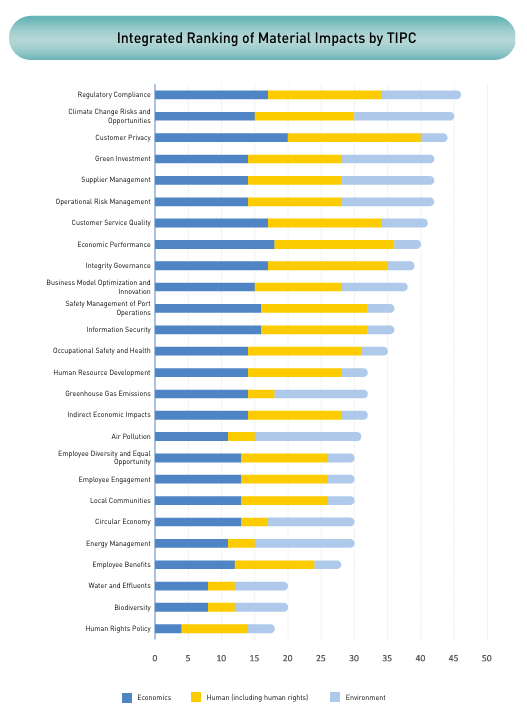
Integrated Impact Ranking of TIPC Materiality
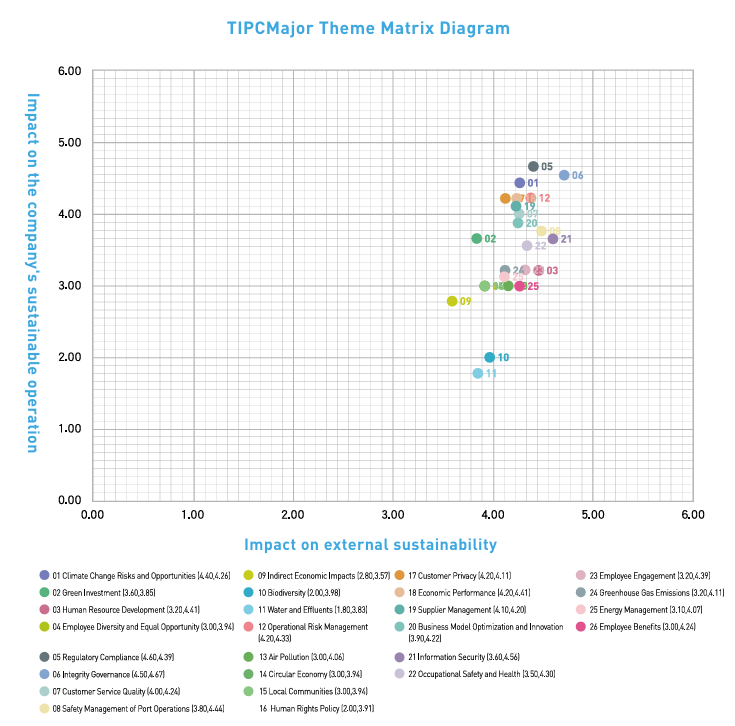
TIPC Materiality Matrix Analysis
To understand the material issues of concern to its stakeholders, TIPC conducted a material topic survey in 2025Note, which served as an important reference for the assessment and discussion of material topics. A total of 102 stakeholders were invited to participate in the survey. The Company also considered stakeholders’ levels of concern regarding various topics as an important basis for sustainable development and strategic planning, enabling it to better respond to stakeholder expectations and needs.